Quantitative finance.
Without the noise.
Research, risk and financial systems engineering grounded in observable data, reproducible methods and explicit assumptions.
Research is only as strong
as its assumptions.
Across fixed income, statistical modeling and execution infrastructure, our focus is on what can be observed, tested and reproduced.
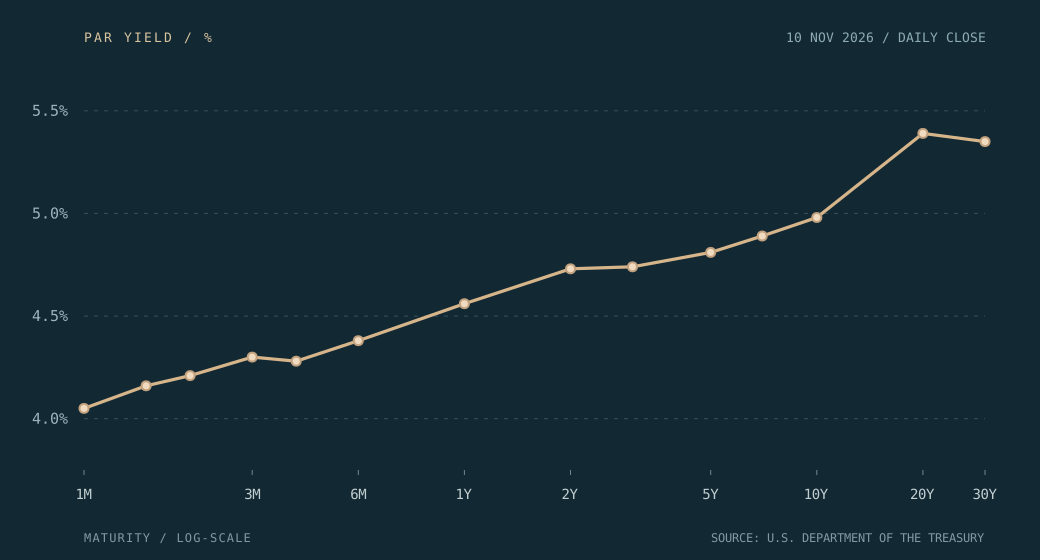
Asset pricing & term structure
Sovereign curves, rate sensitivities, scenario analysis and the limits of yield-based inference.
METHODS & EVIDENCEStatistical risk & validation
Distributional assumptions, dependence, stress tests, point-in-time evaluation and model uncertainty.
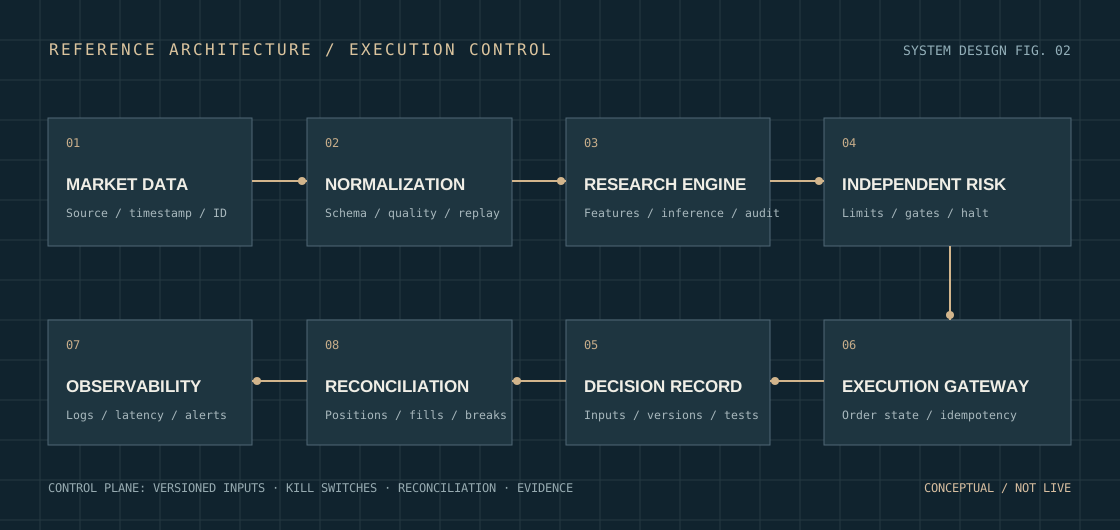
MODEL GOVERNANCEResearch & execution systems
Market-data pipelines, event-driven architecture, deterministic controls and reproducible audit trails.
SYSTEM ARCHITECTUREA financial dataset is not a fact until its provenance survives inspection.
The desk prioritizes original publishers, visible observation dates, and explicit update frequency. Missing inputs remain missing; synthetic numbers never silently substitute for market observations.
Inspect the sovereign curve deskArchitecture is a risk control.
Timestamp discipline, explicit state transitions and reconciliation matter before any forecasting model is introduced.
The research record.
Technical notes written to expose assumptions and invite inspection.