Term-structure analysis
Par-yield conventions, tenor interpolation, slope and curvature, duration and shock scenarios.
Research is evaluated through its data lineage, assumptions, out-of-sample design and economic interpretation.
A yield curve describes a cross section of quoted rates at a particular date; it does not, by itself, identify future returns. That distinction governs how curves, models and scenarios are presented here.
Par-yield conventions, tenor interpolation, slope and curvature, duration and shock scenarios.
Heavy tails, dependence, regime instability, drawdown mathematics and scenario sensitivity.
Point-in-time datasets, embargoed observations, look-ahead leakage and nested validation.
Arrival-price benchmarks, liquidity conditions, stateful order handling and execution costs.
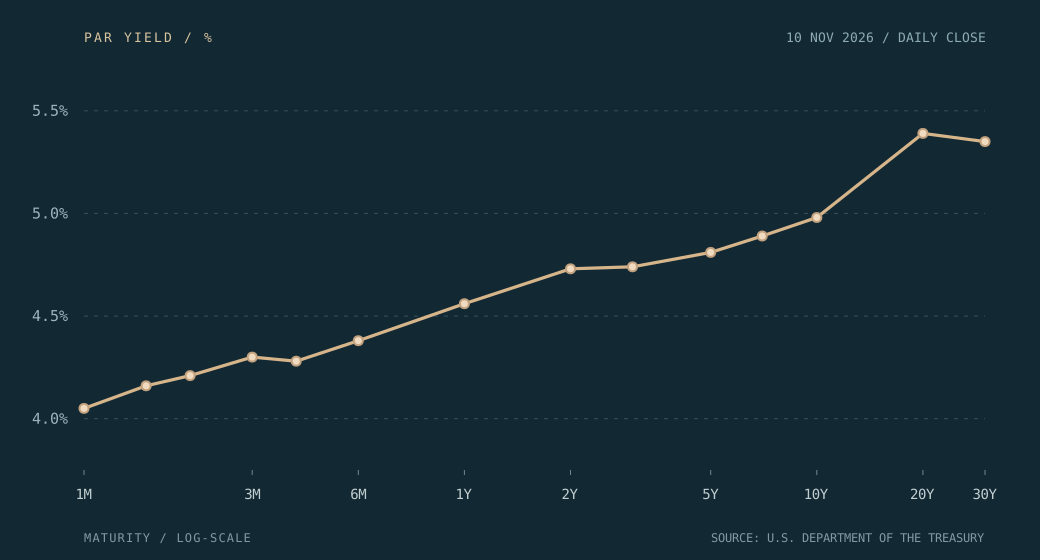
The 2s10s spread is 25 basis points on the displayed observation: 4.98% minus 4.73%. The figure is descriptive, not a forward-rate or return forecast.